Bearaco

Industrials is three businesses. One margin programme will miss the point.

A service-led equipment business, a volume plant and a process asset do not earn margin from the same decisions. Our view is that programmes built around a single industrial cost benchmark risk cutting the capabilities that earn the return. This page is for CEOs, CFOs and boards deciding where to commit capital, reset a footprint or recover margin.

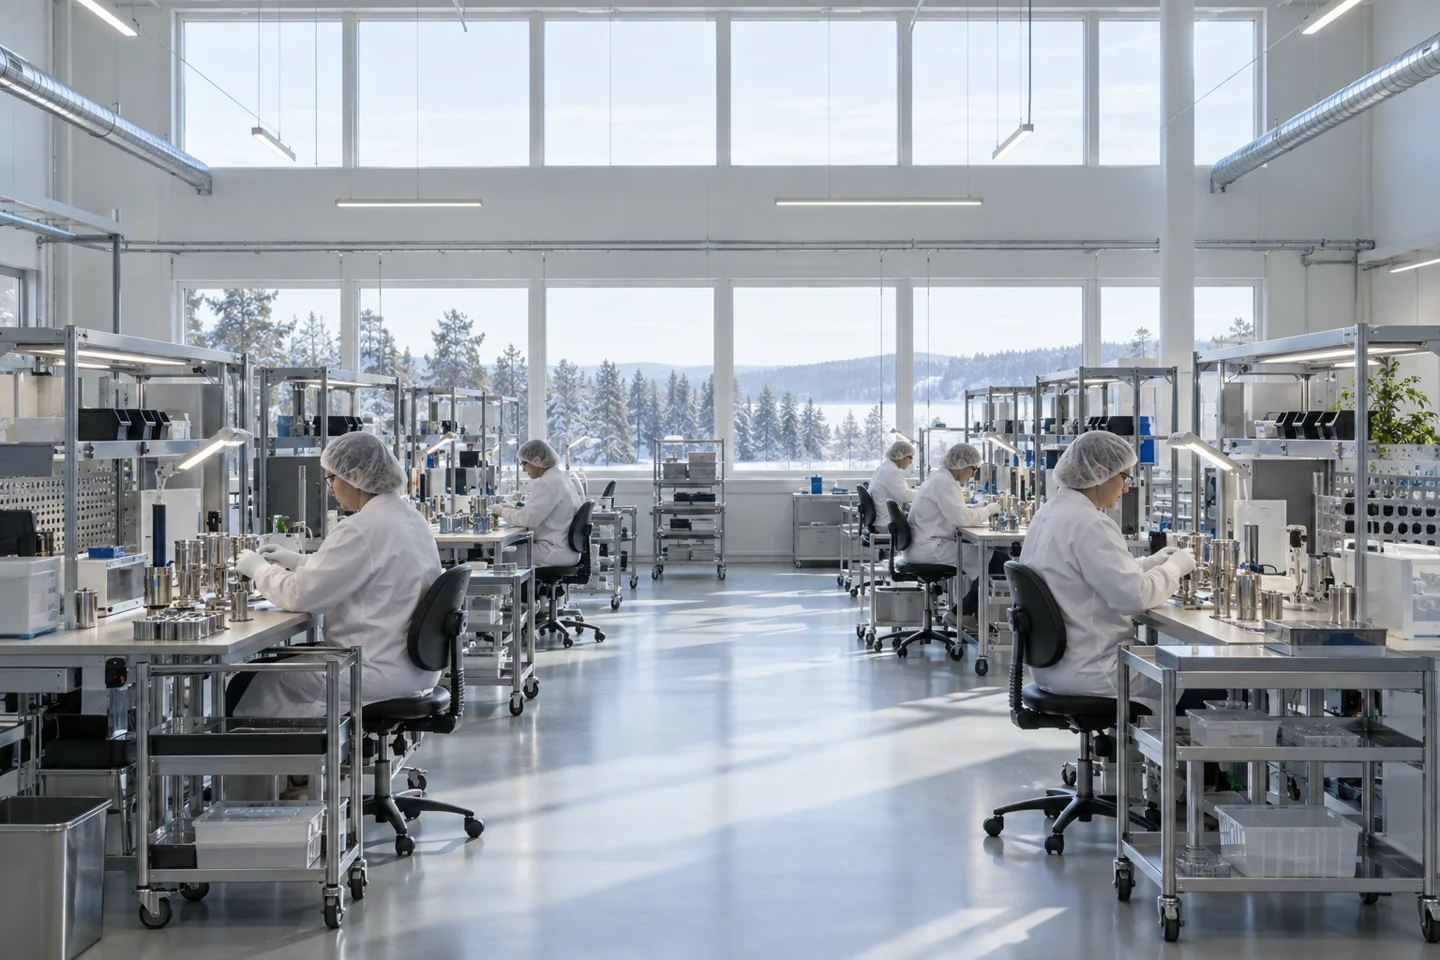
Illustrative Nordic manufacturing hall with precision machinery and a distant worker
Macro editorial photograph of a robotic welding arm joining a steel component, precise sparks in a dark controlled industrial production cell, no trains

How the sector divides

Capital goods with installed base

Margin comes from equipment mix, service attachment and the lifetime cost of keeping the installed base working.

The installed base can matter more than the next equipment order.

Equipment sales add assets that may require parts, maintenance and upgrades for years. When service contracts sit outside the original sales decision, equipment discounts and service obligations can be approved against different profit models.

So what

Assess each equipment offer against lifetime contribution, including warranty exposure and the service capacity it consumes.

Product variety can turn engineering into an unpriced commitment.

Customer-specific variants create engineering, spare-parts and documentation obligations after the initial order. Revenue by product does not reveal those obligations unless engineering effort and lifetime support are assigned to the contract.

So what

Set explicit boundaries for customisation and make exceptions carry their engineering and support cost.

When the decision moves onto your agenda.

  • A major equipment bid is approaching, but warranty, service and spare-parts assumptions sit in separate business cases.
  • Service revenue is missing plan and nobody can reconcile the installed-base register with contracts and renewal dates.
  • An acquisition adds a product platform, and the board must decide which engineering and service capabilities to combine.
Illustrative process manufacturing plant with a worker inspecting stainless steel equipment.

For the board

Use common demand and input-cost scenarios to compare investments, then assign operating measures specific to each business.

Explore shared decisions ↓

Volume manufacturing

Margin comes from contribution per constrained production hour, schedule stability and the cost of product complexity.

Utilisation can improve while contribution deteriorates.

Production targets expressed in units or hours can favour long runs of low-contribution products. Bottleneck capacity is then occupied without testing what each order contributes after material, conversion and fulfilment costs.

So what

Allocate constrained capacity against contribution and delivery commitments, rather than the volume target alone.

A cheaper footprint can consume more cash during transfer.

A site decision changes freight, inventory buffers, validation work and service risk as well as factory cost. Counting the destination’s unit cost before pricing the transition can overstate the value available to fund it.

So what

Approve footprint changes against a cash-funded transfer plan with explicit quality and customer-release gates.

When the decision moves onto your agenda.

  • A customer changes its call-off schedule after the plant has committed labour, material and production slots.
  • A factory investment is ready for approval, but product-level bottleneck economics have not been reconciled with the sales forecast.
  • A site closure has been announced internally, while validation, inventory and customer-transfer costs remain outside the business case.

Process & basic materials

Margin comes from yield, energy and feedstock spread, asset availability and the economics of shutdowns.

Input exposure can move faster than realised selling prices.

Feedstock and energy purchases, customer pricing formulas and contract resets need not move together. A favourable product spread at a quoted market price can conceal a cash squeeze in the actual purchase and sales books.

So what

Manage the contracted spread and reset calendar before committing production or pricing a new customer agreement.

Availability is valuable only when the incremental tonne pays.

Running an asset harder can increase maintenance exposure, off-spec output and energy use. A production target that omits those effects cannot settle the choice between another run and a planned shutdown.

So what

Make shutdown and maintenance decisions against campaign economics, including restart risk and the cost of lost availability.

When the decision moves onto your agenda.

  • An energy or feedstock contract expires before customer prices can be reset.
  • A turnaround is being deferred to protect output, without an agreed estimate of failure and restart exposure.
  • An expansion reaches the investment committee with a single spread forecast and no funded downside case.

The same capital budget hides different commitments.

A common payback rule can choose the wrong investment.

Service capacity, a manufacturing transfer and a process turnaround commit cash on different schedules. Compare cash returns after service obligations, transfer buffers and shutdown risk, rather than ranking headline savings.
One segment’s price increase can be another’s margin squeeze.

Material suppliers, component plants and equipment manufacturers can sit in the same value chain. Reconcile internal transfer prices and external reset dates before adding their recovery plans together.

Cases

Explore all engagements →

Talk it through with a partner.

Bring the investment, footprint or pricing decision that the current margin target cannot resolve. We would map the relevant profit drivers, test the assumptions behind the plan and agree which operating evidence would change the decision.

Bearaco partners

Email a partner